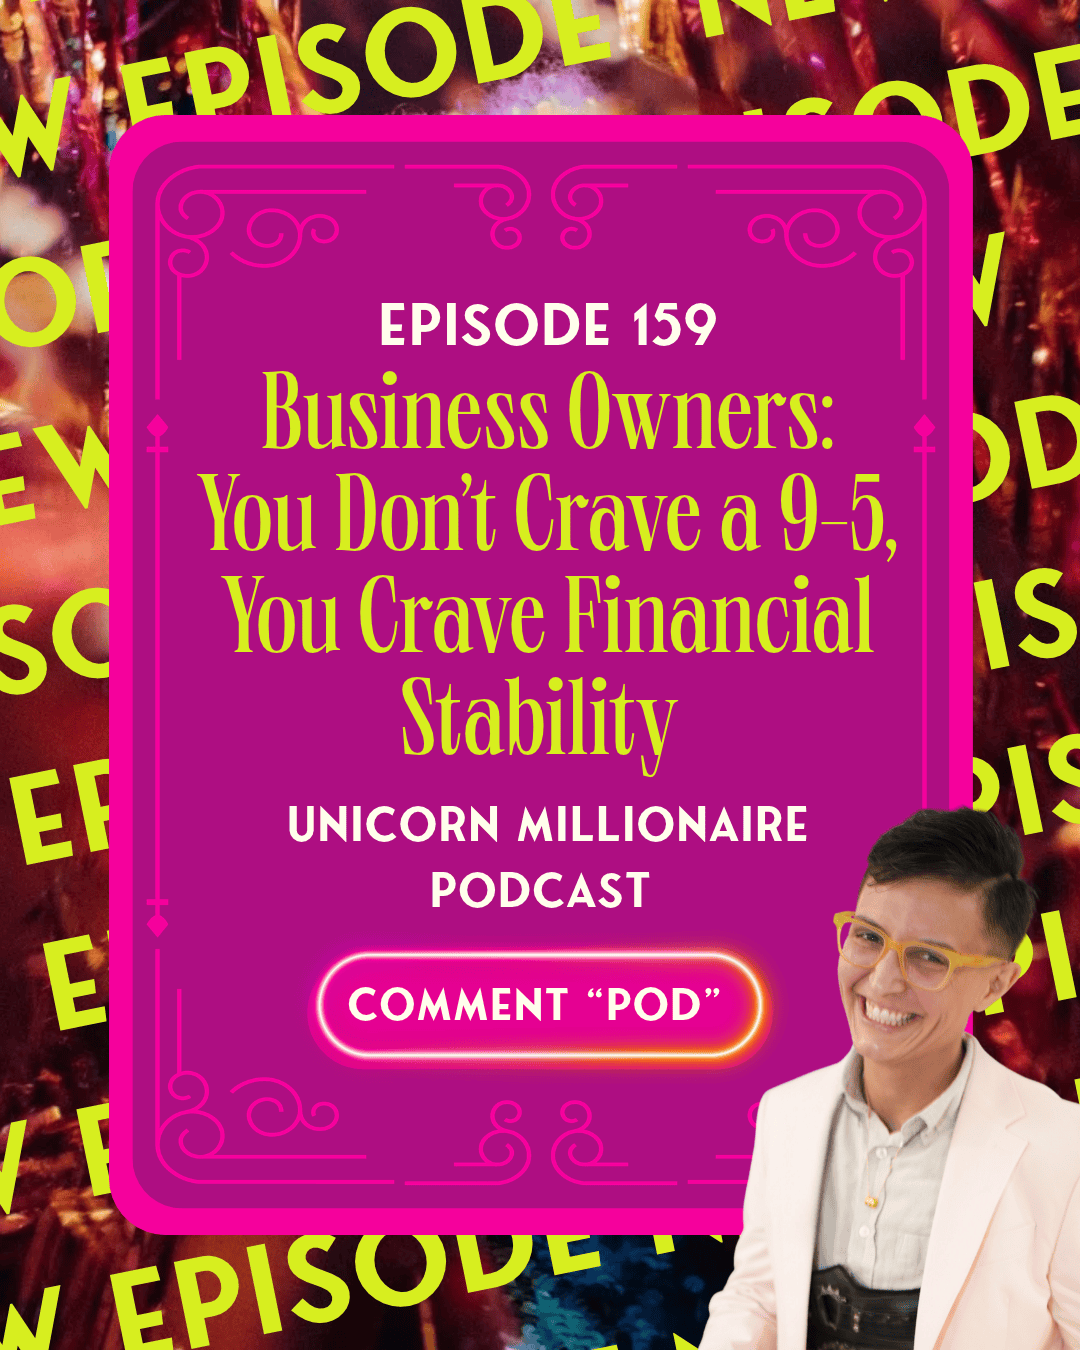
Business Owners: You Don’t Crave a 9-to-5, You Crave Financial Stability | 159
Financial stability for business owners means giving your business income a plan: paying yourself, preparing for uneven months, investing for retirement, and protecting time to enjoy your life. You don’t necessarily need to return to a 9-to-5 to create that structure.
You’re chasing an invoice, sales are inconsistent, and money keeps coming in—but managing it feels messy AF. Then the thought arrives: “Maybe I should just get a job.” When you imagine going back, you probably aren’t picturing the commute, code-switching, or condescending boss. You’re picturing a predictable paycheck, benefits, and someone in HR who knew the answers.
You don’t crave a 9-to-5. You crave financial stability.
Sometimes you’re idealizing that job like an ex you left for a reason. Wanting a job is valid, but wanting more financial structure doesn’t automatically mean entrepreneurship was a mistake. When you left employment, you also took on responsibility for building your own financial systems.
I’ve run my money coaching business since 2020. My business makes around $45,000–$62,000 a year, and I’m a single-income earner with nobody splitting my bills. I run my business from multiple countries, take two months off a year, and prioritize retirement contributions. Those are my circumstances, not a promise that someone else’s numbers will work the same way. They’re a reminder that you don’t have to make six figures before planning for your future.
1. Give retirement a place in your business-owner money plan
I prioritize maxing out my Roth IRA early in the year and also fund my solo Roth 401(k). I don’t max out every retirement account available to me. My contributions have to fit my finances.
If you already reserve money for taxes but retirement still feels confusing, your next step may be learning which accounts you’re eligible for and deciding what you can sustainably contribute. You don’t need to copy my accounts or contribution amounts. Account eligibility, plan rules, and tax circumstances matter.
Start with my guide to Solo 401(k) vs. Roth IRA for business owners for a deeper comparison. Investing involves risk; contributions are not investment gains.
2. Price your services to support a life, not constant availability
My prices need to account for more than the hour I spend on a client call. Preparation, administration, taxes, retirement, and time off all affect what a sustainable business looks like.
A useful starting point is to compare what your business needs to provide with the cost and capacity required to deliver your services. If your plan only works when every possible slot is booked, there’s little room for illness, rescheduling, or rest. More revenue can help, but your pricing and workload deserve attention too.
3. Reinvest intentionally—and keep yourself in the plan
I recently invested $10,000 in business coaching. That was my decision, not a recommendation that every business owner needs expensive coaching. A purchase being “for the business” doesn’t automatically make it worthwhile.
Before reinvesting, consider what the purchase is meant to help you do, whether you’ll use it, and what the expense leaves available for your other priorities. Your business can receive support without your own future getting whatever scraps remain.
4. Get useful benefits from spending you already planned
With my recent coaching investment, I’m earning over $1,000 in cash back while paying zero interest. That doesn’t make the coaching free. It adds value to a purchase I’d already decided to make.
One business-owner client earned about $5,000 in points value in her first year, helping fund trips to Europe, plus over $1,000 in cash back. Points value isn’t the same as cash income, and individual outcomes vary. Interest, fees, and unnecessary spending can erase rewards. The repayment plan matters as much as the offer.
For tax decisions, I work with my accountant rather than guessing about write-offs. Read my year-end business money moves for how I approach planning ahead.
5. Schedule the freedom you left your job for
I plan my days and schedule weekly massages and self-care. Those don’t wait until every email has an answer, because there will always be another email. Structure helps me make space for the life my business is supposed to support.
One client came to coaching burnt out, with a workhorse mentality and a habit of answering emails as they arrived out of scarcity. She went on to max out her retirement accounts and create more breathing room—including more time gardening. Her experience isn’t a guaranteed outcome. It shows why the numbers and the habits around money both matter.
Frequently asked questions about financial stability for business owners
Do I need six figures in revenue to start building wealth?
No single revenue milestone determines when you can begin. Start with your income, expenses, obligations, and available resources. A sustainable plan matters more than copying someone else’s contribution amounts.
Can I feel more stable with inconsistent business income?
A clearer view of cash flow, upcoming obligations, reserves, and owner pay can help you make decisions with less guesswork. Structure can’t guarantee sales, but it can help you prepare for variability.
Does earning credit card rewards make a purchase worthwhile?
Not by itself. Evaluate the purchase first, then the rewards, fees, interest, and repayment terms. Don’t spend extra just to earn a bonus.
Listen to Unicorn Millionaire Podcast Episode 159
Hear the full conversation in Business Owners: You Don’t Crave a 9-to-5, You Crave Financial Stability | 159. Find this episode on Apple Podcasts
Build your plan with six-month money coaching
In my six-month private money coaching, we look at your personal and business finances together: what comes in, where it goes, and what needs to change so your money supports you. We work on paying yourself, pricing, saving and investing, and understanding benefits that fit your situation. We also address the scarcity that makes rest feel irresponsible.
You already know how to work hard for your business. Let’s make sure your business is working for you. Learn about six-month money coaching · Book a clarity call · Join my free Dom Your Dinero emails
Reading before November 10, 2026? Join my free live webinar, Business Owners: Find $10K+ in Hidden Business Benefits Before 2027, on Tuesday, November 10 at 1 PM PT / 4 PM ET. About 60 minutes, including live Q&A, with no replay. Register for the business webinar. Reading afterward? Learn about six-month money coaching · Book a clarity call · Join my free Dom Your Dinero emails
About Charly: I’m Charly Stoever (they/he), a nonbinary Latinx money coach, former stockbroker, and host of Unicorn Millionaire. I help LGBTQ+, BIPOC, first-gen, and neurodivergent folks optimize cash, credit, and investments with their current income so they can be their own sugar daddy now and still retire early.
Featured photo: Katie Mont on Unsplash.
Educational information, not individualized tax, legal, or investment advice. Client experiences are individual examples, not guaranteed results.